
Getting paid every two weeks sounds simple until your bills refuse to cooperate. Rent, council tax, phone and credit card payments all arrive on monthly dates, while your income lands every 14 days. One paycheck gets swallowed by rent, and the next feels like a windfall. If that cycle sounds familiar, the problem usually isn’t your income. It’s the mismatch between two different calendars.
This guide shows you how to budget bi-weekly pay step by step: how to map your bills, assign each one to a paycheck, smooth out the big expenses and use the extra paychecks that turn up during the year. It works in both the US, where bi-weekly pay is common, and the UK, where fortnightly and four-weekly pay schedules have the same problem.
Why bi-weekly budgeting feels broken
Most bills are monthly, but a bi-weekly schedule pays you every 14 days. A year has 52 weeks, so you usually receive 26 paychecks a year, not 24. In most years that means two months contain three paydays.
If you budget as if every month gets exactly two paychecks, you’ll feel stretched in some months and oddly flush in others. If you budget as if every month gets “about 2.17 paychecks”, you’ll come up short whenever a big bill lands before payday.
UK readers: fortnightly pay works the same way. If you’re paid every four weeks, you receive 13 payments a year, so one month each year contains two paydays. The same system below applies.
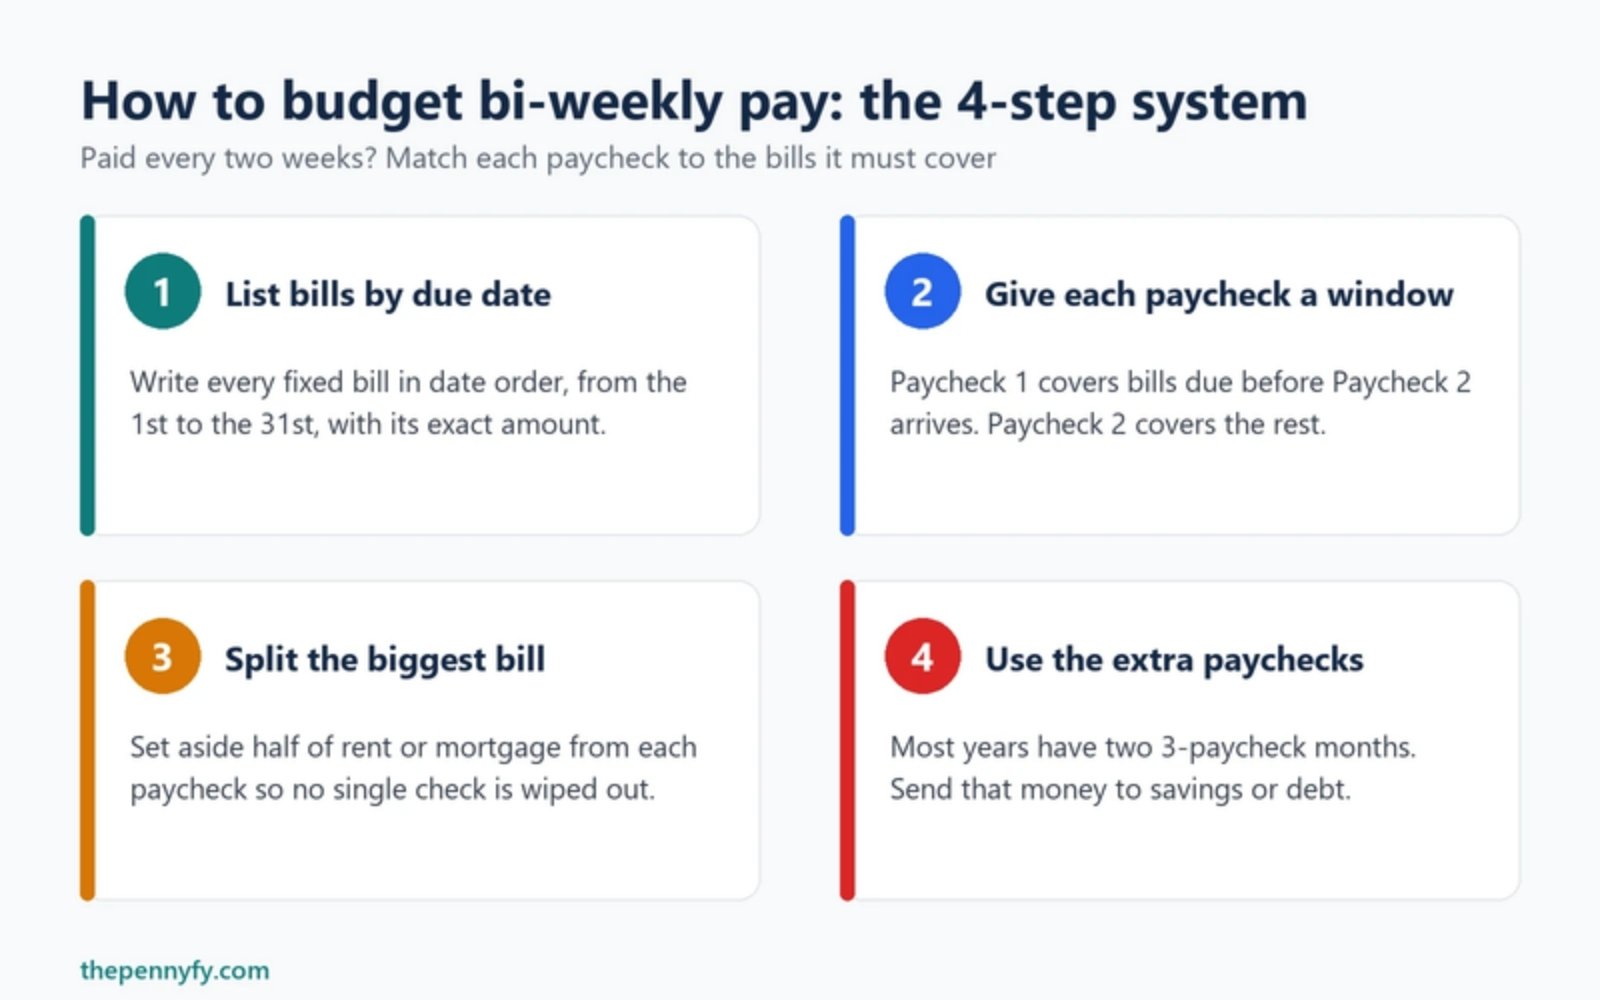
How to budget bi-weekly pay: the 4-step system
Step 1: List every fixed bill by due date
Open your banking app and look back over the last two months. Write down every recurring payment, its amount and its due date, in order from the 1st to the 31st. For example:
| Bill | Amount (US / UK example) | Due |
|---|---|---|
| Rent or mortgage | $1,200 / £950 | 1st |
| Car loan or travel pass | $300 / £200 | 8th |
| Energy and broadband | $200 / £150 | 14th |
| Phone, insurance, subscriptions | $80 / £60 | 22nd |
Example figures only. Use your own bills.
Step 2: Give each paycheck its own “window”
Instead of thinking in months, think in pay periods. Each paycheck is responsible for the bills due before the next paycheck arrives.
Say you’re paid on the 3rd and the 17th:
- Paycheck 1 (3rd-16th) covers bills due in that window, such as the car loan (8th) and energy (14th).
- Paycheck 2 (17th-2nd) covers the 22nd bills and next month’s rent on the 1st.
Write the windows on a calendar or in a spreadsheet so you can see at a glance which check pays for what.
Step 3: Split the biggest bill across both paychecks
The most common problem is one paycheck carrying almost all of your fixed costs, usually because of rent or a mortgage. Fix it by setting aside half of that bill from each paycheck.
With $1,200 / £950 rent due on the 1st, move $600 / £475 from each paycheck into a separate “bills” account. When the 1st arrives, the full amount is already there, and neither paycheck is wiped out.
UK tip: council tax is usually split into 10 monthly payments, but you can ask your council to spread it over 12 instead, according to GOV.UK. Smaller payments are easier to fit into a two-week cycle.
Step 4: Budget variable spending per paycheck, not per month
Groceries, fuel, eating out and entertainment are easier to control in two-week chunks. If you spend about $400 / £320 a month on groceries, give yourself $200 / £160 per paycheck. A two-week limit is easier to stick to than a monthly one, because you can’t overspend in week one and run dry in week four.
What to do with the extra paychecks
If your regular costs are covered by two paychecks a month, the third paycheck in a three-paycheck month is free money for your goals. Decide in advance where it will go, before it gets absorbed into everyday spending:
- Emergency fund: build towards a cushion; many guides suggest three to six months of essential costs.
- High-interest debt: clear credit cards first. Our debt snowball vs avalanche guide helps you choose an order.
- Long-term saving: top up a 401(k) or IRA (US), or a workplace pension or Stocks and Shares ISA (UK). See ISA vs 401(k) for how they compare.
Bi-weekly budget at a glance
| Paycheck | Main job | Typical bills covered |
|---|---|---|
| First paycheck of the month | Bills due before the next payday + half of next month’s rent | Loans, utilities, groceries for 2 weeks |
| Second paycheck of the month | Late-month bills + the other half of rent | Phone, insurance, credit card payment, savings transfer |
| Extra paycheck (usually twice a year) | Goals only | Emergency fund, debt payoff, retirement or ISA |
Tips to make it run smoothly
- Use two accounts. One for bills (where your split amounts build up) and one for day-to-day spending. When the spending account is empty, you know you’ve hit your limit.
- Ask to move due dates. Some lenders, card issuers and utility companies may move a payment date if you ask. Line bills up just after payday.
- Automate on payday. Schedule the bills-account transfer and your savings transfer for the morning your pay arrives.
- Budget from take-home pay. In the US, 401(k) contributions and taxes come out before your paycheck lands. In the UK, pension contributions, tax and National Insurance do. Plan around what actually reaches your account.
- Keep a small buffer. A cushion of one week’s spending in your bills account covers timing slips without dipping into an overdraft.
If you’re new to budgeting, combine this system with the 50/30/20 rule, and watch out for lifestyle creep when your pay rises. For more habits that build on this, see our 25 personal finance tips.
Frequently asked questions
How many paychecks do you get a year if you’re paid bi-weekly?
Usually 26, because there are 52 weeks in a year. Depending on how the calendar falls, some years have 27.
What is the easiest way to budget bi-weekly pay?
Assign each bill to the paycheck that arrives before it’s due, split your rent or mortgage across both paychecks, and budget variable spending per two-week period.
What should I do with the third paycheck?
Send it straight to a goal you’ve chosen in advance, such as your emergency fund, credit card debt or retirement savings, rather than everyday spending.
Does this work if I’m paid every four weeks in the UK?
Yes. You’ll get 13 payments a year, so one month contains two paydays. Treat that extra payment the same way as a third bi-weekly paycheck.
Should I budget using my gross or net pay?
Always use net (take-home) pay, the amount that actually reaches your bank account after tax and deductions.
The bottom line
Bi-weekly pay feels chaotic only when you force it into a monthly budget. List your bills by date, give each paycheck a clear job, split the big costs across both checks and plan the extra paychecks in advance. Spend an hour setting it up this weekend, and payday stops being a rollercoaster.
This article is general information, not personal financial advice. Last reviewed October 2026.
Related reading: budgeting when you are too stressed to look at your bank account