

Debt snowball vs avalanche is the classic question for anyone juggling several debts. Picture four card statements spread across a kitchen table: two store cards, a travel card and an “emergencies only” card that slowly turned into an everyday card. Do you clear the smallest balance first for a quick win, or attack the highest interest rate to save money?
That argument, small balance first versus highest rate first, is the entire debt snowball versus debt avalanche debate. Both methods work. Neither is a scam or a gimmick. But they solve different problems, and picking the wrong one for your personality can leave you stuck exactly where you started.
This guide breaks down both methods with real numbers, shows you which one actually saves more money, and helps you figure out which approach you’ll stick with long enough to see your balances hit zero.
What Is the Debt Snowball Method?
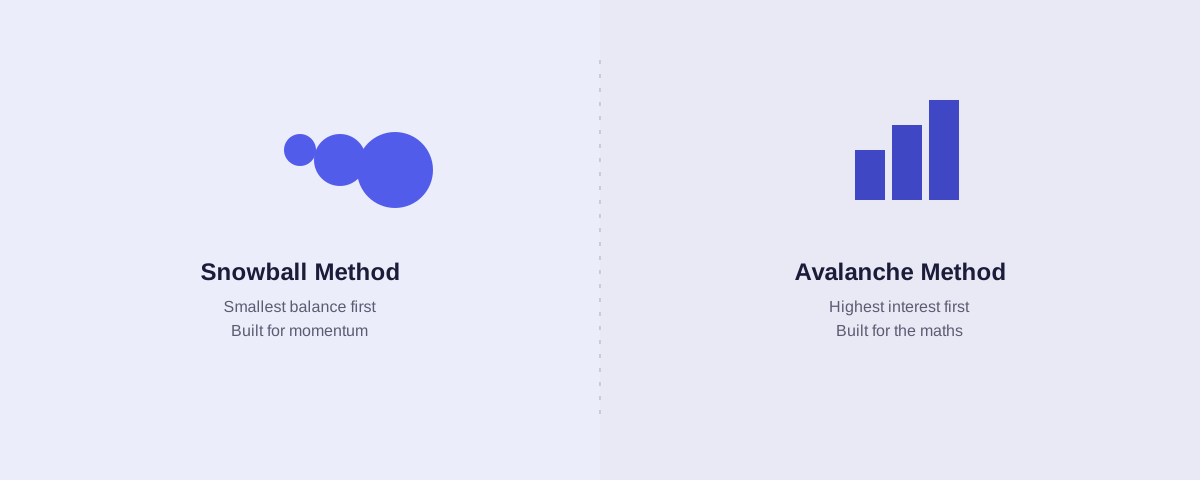
The debt snowball method has you list every debt from smallest balance to largest, completely ignoring interest rates. You make minimum payments on everything except the smallest debt, and you throw every spare dollar at that one until it’s gone. Once it’s paid off, you roll that payment amount into the next smallest debt, and so on.
The appeal is obvious. You get a win early, sometimes within a month or two, and that win keeps you motivated to keep going. Dave Ramsey popularized this approach for exactly that reason: personal finance is only half math, the other half is behavior.
What Is the Debt Avalanche Method?
The debt avalanche method flips the order. You still make minimum payments on every debt, but your extra money goes toward whichever balance has the highest interest rate first, regardless of size. Once that one is cleared, you move to the next highest rate.
Mathematically, this is the more efficient method almost every time. Interest is what makes debt expensive, so killing the highest-rate balance first means less of your money gets eaten by interest charges over the life of your payoff plan.
Debt Snowball vs Avalanche: Side-by-Side Comparison
| Debt Snowball | Debt Avalanche | |
|---|---|---|
| Payoff order | Smallest balance first | Highest interest rate first |
| Best for | People who need motivation and quick wins | People who are disciplined and focused on saving money |
| Total interest paid | Usually higher | Usually lower |
| Time to first win | Depends on balance size | Can take longer if the highest-rate debt is also large |
| Psychological reward | High, early momentum | Lower at first, builds over time |
| Math outcome | Good | Best |
A Real Numbers Example
Numbers make this click faster than theory does, so here’s a worked example using rates close to what US and UK cardholders are actually paying right now. According to the Federal Reserve’s consumer credit data, the average rate on US credit card accounts that were charged interest was 22.15% in the second quarter of 2026. UK card rates vary by provider, so check the APR on your own statements.
Say you have three debts:
- Card A: $1,200 balance, 26% APR
- Card B: $3,500 balance, 19% APR
- Card C: $5,800 balance, 24% APR
You have $400 a month to put toward extra payments, on top of minimums.
With the snowball, you’d attack Card A first since it’s the smallest. It clears fastest, giving you a quick psychological win. But Card C, your biggest balance, sits there accumulating interest at 24% for months while you focus elsewhere.
With the avalanche, you’d attack Card A first too in this case, since it happens to carry both the smallest balance and the highest rate. Then you’d move to Card C (24%) before Card B (19%), even though Card C is the larger balance.
We ran these numbers ourselves, assuming interest of one twelfth of the APR each month, fixed minimum payments of $35, $90 and $150 plus the extra $400 ($675 a month in total). Both methods clear all three cards in 19 months, but the avalanche costs about $143 less in interest ($1,934 vs $2,078). The gap gets bigger with larger balances and a wider spread of interest rates. With small balances and similar rates, it can be close to zero.
Why the Avalanche Method Saves You More Money
The math is simple once you see it laid out: interest compounds on whatever balance is left, so the longer a high-rate debt survives, the more it costs you. Every month that a 26% APR card carries a balance, it’s quietly adding more to what you owe than an 18% card would. The avalanche method minimizes the total amount of time your most expensive debt exists, which is exactly why it wins on paper almost every time.
If you’re the type of person who can look at a spreadsheet, trust the process, and not need a dopamine hit every few weeks, avalanche is very likely your better option.
Why the Snowball Method Might Still Be the Right Choice
Here’s the thing nobody likes to admit: paying off debt is at least as much a behavior problem as it is a math problem. In a 2016 Harvard Business Review article, researcher Remi Trudel and colleagues reported that focusing on the account with the smallest balance tends to have the strongest effect on people’s sense of progress, and therefore on their motivation to keep paying down debt. That’s the snowball’s real advantage, even though it usually costs a little more in interest. He notes that this advice applies when your debts carry similar interest rates.
If you’ve tried to tackle debt before and lost steam three months in, or if just looking at your total balance makes you want to close the laptop and pretend it doesn’t exist, the snowball’s quick wins might be worth the extra interest cost. A payoff plan you actually finish beats a mathematically perfect one you abandon.

The Hybrid Approach: Snowball Then Avalanche
You don’t have to pick a side forever. A lot of people start with the snowball to build momentum and prove to themselves that this is actually working, clear one or two small debts to get that early confidence boost, then switch to avalanche mode once the habit sticks. This hybrid approach is unofficial, nobody’s put a fancy name on it, but it’s genuinely one of the most practical ways to get the psychological benefit of the snowball without giving up all the interest savings of the avalanche.
Common Mistakes People Make With Either Method
Not tracking minimum payments carefully. Both methods only work if you’re still making minimums on every other debt. Missing one, even while aggressively paying down another, can trigger penalty APRs or late fees that undo your progress.
Ignoring the emergency fund entirely. Throwing every spare dollar at debt with zero savings buffer means one car repair or broken boiler sends you right back onto a credit card. Keep a small starter emergency fund before going all-in on either method.
Switching methods every few months. Picking a method and abandoning it after six weeks because progress feels slow defeats the purpose. Give whichever method you choose at least a few months before deciding it’s not working.

Not accounting for promotional 0% APR periods. If one of your cards is on a 0% introductory rate that’s about to expire, treat it as if it already carries its post-promo rate when deciding what to pay off first under the avalanche method.
Forgetting to close the tap while you’re paying it down. Aggressively paying off Card A while still swiping Card B for everyday spending just refills the bucket you’re trying to empty. Both methods assume you’ve stopped adding new debt on top of what you’re clearing. If you’re still relying on credit for regular purchases, it’s worth reading up on how to pay a credit card bill the right way so you’re not accidentally working against yourself.
Which Method Should You Actually Choose?
Choosing between debt snowball vs avalanche comes down to a few honest questions:
- Do I need to see progress fast to stay motivated, or can I trust a long-term plan without regular wins?
- Is the gap in interest rates between my debts large (10%+ difference) or fairly small?
- Have I tried and abandoned a debt payoff plan before?
If you answered yes to needing quick wins or have a history of losing motivation, start with the snowball. If your interest rate gap between debts is large and you’re confident you’ll stick with the plan regardless of pace, the avalanche will save you real money. And if you’re not sure, the hybrid approach removes the pressure of picking perfectly on the first try.
Whichever you choose, pairing it with a clear 50/30/20 budget makes it far easier to find that extra payment amount each month without feeling like you’re white-knuckling your way through it.
Frequently Asked Questions
Is debt snowball or avalanche better for credit score?
Neither has a direct advantage for your credit score specifically. What helps your score is reducing your overall credit utilization and making every payment on time, both of which happen under either method. If your credit score is the main concern, check where you currently stand before you start.
Can I use these methods for a debt management plan?
Yes, though if you’re already working with a debt management plan, your provider may have already restructured your interest rates, which can change which debts make sense to prioritize. UK readers who want free, government-backed guidance before choosing a plan can also speak with MoneyHelper, which offers free, impartial guidance.
How long does it typically take to pay off debt with either method?
It depends entirely on your total balance, average interest rate, and how much extra you can pay each month. At 22.15% APR on a $10,000 balance (fixed rate, no new spending), a total monthly payment of $300 takes about 53 months, $400 about 34 months and $500 about 26 months.
Should I stop investing while paying off debt?
High-interest debt usually deserves priority over extra investing, but keep contributing enough to get any employer retirement match, since that is essentially free money.
What if my debts have similar interest rates?
If the rates across your debts are within a couple of percentage points of each other, the avalanche method’s savings shrink to almost nothing, and you might as well use the snowball for the motivational benefit since you’re not giving up much in interest either way.
Final Thoughts
There’s no version of this where picking snowball over avalanche, or the other way round, ruins your finances. Both methods have gotten real people out of real debt. The one that actually works is the one you stick with until your balances hit zero, so be honest with yourself about which kind of motivation keeps you moving, run your own numbers with your actual balances and rates, and start this month rather than waiting for the “perfect” plan.
If you haven’t already, it’s worth checking your credit score for free before you start, so you’ve got a clear before-and-after picture as your balances come down.
This article is for general information and education only. It is not personal financial advice. Rules, rates and allowances change, so check official sources (GOV.UK, FCA or MoneyHelper in the UK; IRS, CFPB or SEC in the US) before you decide. See our Disclaimer and Editorial Policy. Last reviewed October 2026.
Related reading: budgeting when you are too stressed to look at your bank account